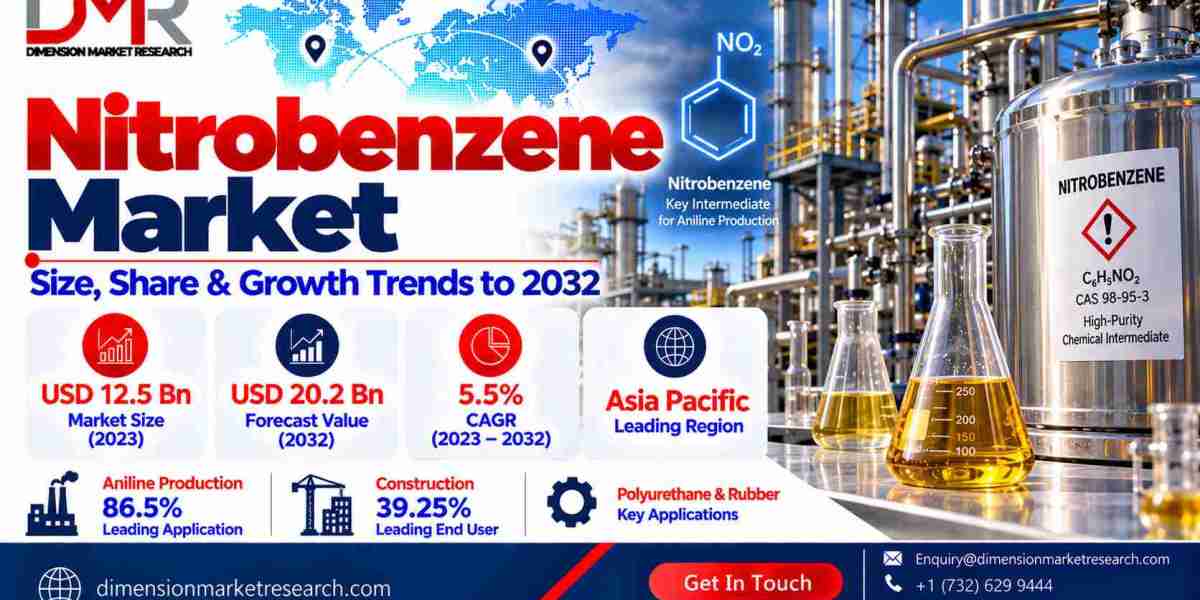
The Nitrobenzene Market connects chemical intermediates with demand across industrial supply chains. According to Dimension Market Research, the report estimates USD 12.5 billion in 2023, forecasting USD 20.2 billion by 2032, at 5.5% CAGR during 2023-2032. These figures represent the report’s stated timeframe.
For chemical manufacturers, procurement teams, and investors, the opportunity requires understanding where downstream demand originates. Evaluating customer industries, production economics, and supply reliability can make the forecast more useful for commercial planning.
What Is the Nitrobenzene Market?
The market covers nitrobenzene production, distribution, and use, primarily as an intermediate for aniline. The report also examines applications in pesticide additives, synthetic rubber manufacturing, and paint solvents.
For business readers, this scope separates the chemical’s direct purchasers from the industries ultimately influencing consumption. A producer assessing expansion should identify which customers would absorb additional output and how their purchasing requirements differ.
That distinction also helps buyers frame supplier assessments around their own production needs.
Get a Free Sample of the Nitrobenzene Market Report
Evaluating supply opportunities, customer demand, or investment priorities? Request a free sample to review the report’s scope and assess its relevance to your business questions.
https://dimensionmarketresearch.com/request-sample/nitrobenzene-market/
Aniline Production Anchors Demand
Aniline production accounts for 86.5% of nitrobenzene consumption in 2023 in the report.
For suppliers, this concentration suggests prioritizing customer relationships within the aniline value chain. Commercial planning should test expected purchasing volumes, qualification requirements, and the extent to which individual accounts influence plant utilization.
For investors, the same finding raises a practical question: how diversified is the proposed revenue base? A business may serve several customers while remaining exposed to similar downstream demand conditions.
A useful assessment would therefore examine both customer concentration and application exposure. This can help distinguish a broad sales pipeline from a genuinely diversified demand base.
Construction Connects Intermediate Chemicals With End Use
The report identifies construction as the leading end-user industry. It connects demand with MDI-based polyurethane, adhesive, sealant, and elastomer applications.
For strategy teams, this suggests tracing the route from chemical sales to specific material applications. A broad construction outlook becomes more actionable when translated into identifiable customers, product requirements, and purchasing decisions.
Producers considering additional capacity should explain which demand assumptions support the investment. Procurement teams can apply the same discipline when reviewing expected consumption and contracting requirements.
This approach helps avoid treating an expanding end market as sufficient evidence for every supplier’s growth plan.
Supply Economics Deserve Equal Attention
Raw material availability, price fluctuations, and regulatory requirements influence the market’s operating environment.
For manufacturers, this suggests testing investment assumptions across several input-cost scenarios. A project assessment should explain how changes in purchasing costs would affect margins, production schedules, and working capital.
Buyers can strengthen supplier reviews by examining delivery commitments, escalation procedures, and the support available when supply conditions change. These considerations help connect price negotiations with production continuity.
For both sides, clear contract assumptions can improve the quality of commercial discussions. Expected volumes, delivery responsibilities, and agreed specifications should be understood before either party commits resources.
Asia Pacific Leads Production and Consumption
Asia Pacific leads the report’s regional analysis, supported by manufacturing infrastructure and aniline and MDI production capacity.
For expansion teams, regional leadership provides a starting point for investigation. Location decisions still require assessment of customer access, input sourcing, transport arrangements, and operating capabilities.
An investor comparing sites could use consistent assumptions to examine these factors. That would make the trade-offs clearer than selecting a location solely because it belongs to the largest regional market.
Companies seeking customers outside their existing footprint should likewise establish how they would serve those accounts reliably.
Competition Requires a Defined Proposition
Companies covered include BASF SE, Covestro AG, Dow, Huntsman International LLC, Wanhua, and Sadhana Nitro Chemical Ltd.
For prospective entrants, competitive assessment should focus on the buyer’s decision. What would encourage a customer to qualify another supplier? Which requirements must be demonstrated before commercial discussions can advance?
Established suppliers can use those questions to review account priorities. Investment in capacity should be accompanied by a clear explanation of customer relevance, delivery capabilities, and the resources needed to support the proposed business.
View the Nitrobenzene Market Report and Purchase Options
Explore the report’s forecast, application segmentation, regional analysis, and competitive coverage to inform supplier assessment, customer prioritization, or capacity planning. Review available licenses and purchase options on the report page.
https://dimensionmarketresearch.com/report/nitrobenzene-market/
Frequently Asked Questions
What market size does the report estimate for 2023?
USD 12.5 billion.
What is the forecast value for 2032?
USD 20.2 billion.
What CAGR does the report provide?
5.5% during 2023-2032.
Which application leads consumption?
Aniline production, accounting for 86.5% in 2023.
Which region leads the market?
Asia Pacific leads production and consumption.
Conclusion
Nitrobenzene’s outlook is closely connected with aniline and construction-related material demand. For businesses evaluating opportunities through the report’s forecast period, the priority is translating downstream demand into realistic customer and operating plans. Capacity decisions should account for supply economics alongside the potential for additional sales.
Related Chemical Market Insights
The Polyurethane Foam Market Size report estimates USD 63.5 billion in 2026, forecasting USD 118.3 billion by 2035, at 7.2% CAGR. Its coverage of insulation, automotive, furniture, and bedding applications provides broader context for businesses examining polyurethane demand.
The Thermoplastic Polyurethane Market Share analysis estimates USD 3.7 billion in 2026, reaching USD 7.0 billion by 2035, at 7.5% CAGR. It examines material chemistries, processing methods, and applications including footwear, automotive components, and medical devices.